

Park National Bank
by Park National Corporation
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
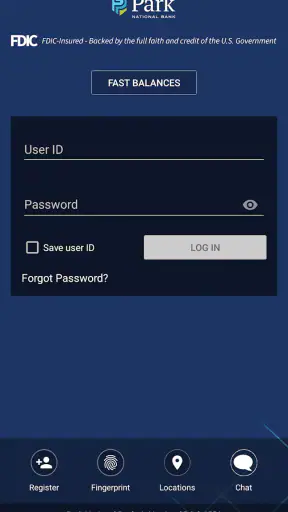
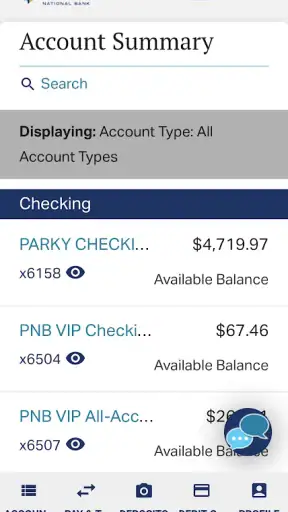
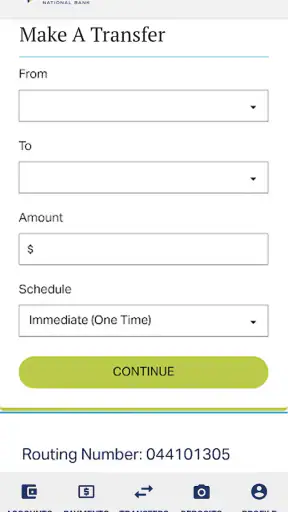
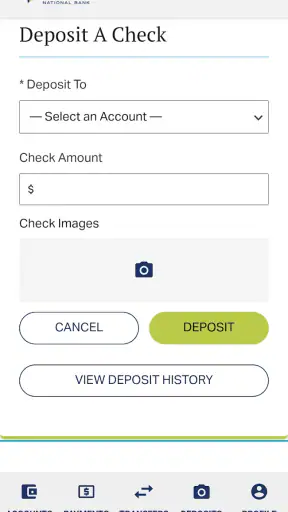
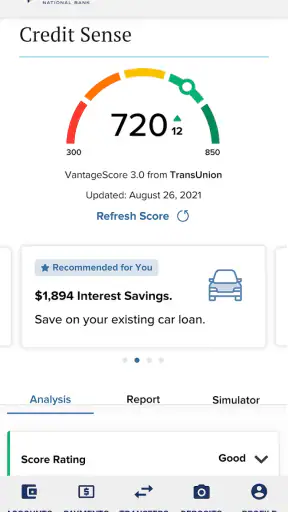
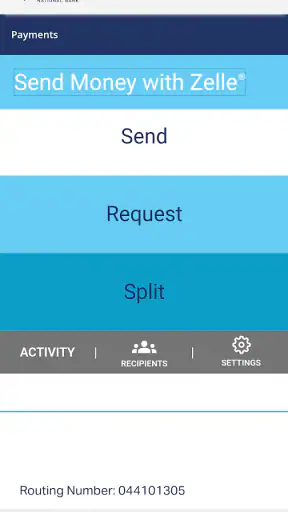
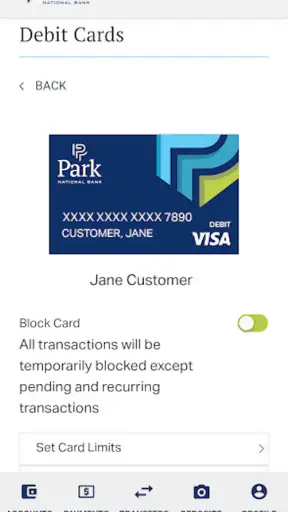
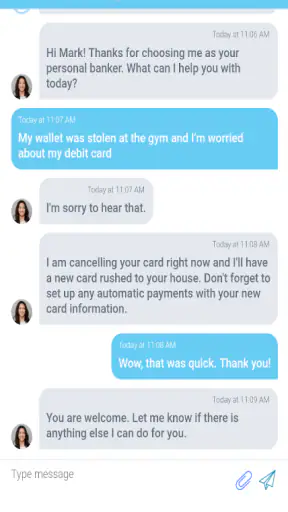
 Analysis by Getfullapps
Managing a bank account from a phone is useful only when the experience feels dependable at the moment I need it. Park National Bank Mobile Banking App is a free finance app from Park National Corporation, built for customers who want to handle everyday banking without opening a desktop browser. I approached it less like a feature checklist and more like a practical tool: how quickly it gets me to a balance, how comfortable it is during a busy day, and whether it remains useful when my phone, connection, or attention is limited.
My overall impression is that this is a focused companion for Park National customers rather than a general-purpose money manager. It is not trying to replace budgeting software, investment platforms, or a full financial dashboard. Its value comes from putting routine bank access in one place. That narrow purpose is also its main boundary: if you do not use Park National, there is little reason to install it, and if you expect broad account aggregation, you should look elsewhere.
What daily banking feels like in practice
The app sits in the finance category and carries an Everyone age rating, which fits its straightforward role. The developer is Park National Corporation, and the app has been available since May 7, 2013. Its current version is 25.2.0 and it requires at least iOS or Android 11, depending on the device you use. Those details matter because banking software should not be treated like a casual utility: keeping the operating system current is part of maintaining a sensible security and compatibility baseline.
When I use a bank app, I want the first few seconds to answer a simple question: what is happening with my money? A good mobile banking routine usually begins with checking an available balance, reviewing recent activity, or confirming that a payment has gone through. Park National Bank is best judged against that expectation. It is a direct route into the banking relationship, not a place where I would spend time exploring charts or customizing a financial plan.
The practical advantage is concentration. Instead of remembering to check a browser bookmark, I can keep the banking task beside the other tools I use during the day. That is especially handy after a purchase, before a transfer, or while checking whether an expected transaction has appeared. I would still take a moment to verify the account and transaction details before confirming anything important, because the convenience of a mobile screen should not encourage rushed decisions.
One useful habit is to separate “checking” from “acting.” I can open the app simply to review activity, then close it rather than turning every visit into a payment or transfer session. This reduces the chance of tapping through a transaction while distracted. For people who frequently monitor spending in short bursts, that small workflow is more valuable than a long list of secondary features.
Speed expectations without unrealistic promises
I would describe the expected experience as task-oriented rather than performance-focused. A banking app does not need to entertain me or load a large media library; it needs to present account information clearly and let me complete a small number of important actions. That makes perceived speed depend on more than the app itself. The phone, operating system, network quality, account service, and authentication process all influence how quickly a screen becomes useful.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
On a strong connection and a reasonably current device, the best experience should feel like opening a dedicated doorway to Park National rather than navigating a full website. The benefit is reduced friction: I am already on a phone, and the app is designed for that context. On a weak connection, I would not treat a delay as proof that the app is broken. Financial information has to be retrieved carefully, and I would rather wait for a trustworthy result than rely on stale information.
That distinction is important when checking an available balance before a purchase. If the screen takes longer than expected, I would avoid repeatedly tapping buttons or starting the same action again. Repeated attempts can create confusion about whether a request was accepted. My safer approach is to wait, look for a clear confirmation, and then review recent activity before trying again. This is a simple but non-obvious advantage of treating the app as a financial instrument rather than an ordinary social or shopping app.
The app’s rating of 4.4 from around 2.8 thousand ratings suggests that many users find the overall experience useful, though a rating alone cannot tell me how it behaves on every phone or network. I read that figure as a sign of solid general acceptance, not as a guarantee of instant loading. Banking performance is highly situational, and the most important test is whether the app gives me a clear state after an action.
Heavy-use moments reveal the real trade-offs
The most demanding moments are not necessarily long sessions. They are short periods when I need several pieces of information close together: checking a balance, reviewing recent transactions, confirming an expected deposit, and then deciding whether to make a payment or transfer. A focused bank app can feel efficient here because the task remains within one financial context. The trade-off is that I should not expect the broader planning tools found in dedicated budgeting apps.
A realistic example is a busy morning before leaving home. I notice an unfamiliar transaction, check the account activity, and then need to decide whether it is a normal purchase or something that deserves follow-up. A useful mobile banking workflow lets me investigate before acting. I would take a screenshot only if appropriate and safe, avoid sharing sensitive account information, and use the bank’s established support route if the transaction remains unclear. The app can make the first review convenient, but it cannot replace careful judgment.
Another heavy-use situation is travel. I may check the account several times in a day, especially before using a card or paying for transport and accommodation. This is where resource demands and connectivity become practical concerns. I would avoid assuming that every screen will be equally available offline, and I would not rely on a previously displayed balance as proof of the current account state. Before traveling, I would make sure the phone is updated, the app is installed from the official store, and I know how to reach the bank if access becomes difficult.
The app is also more useful for frequent small checks than for a long monthly review. For a monthly review, I prefer a larger screen where transaction descriptions are easier to compare and notes are easier to keep. The phone is excellent for immediate awareness; it is less comfortable as the only place to analyze a complicated spending pattern. That is a meaningful boundary for anyone deciding whether this should become their main financial tool.
There is a second trade-off during busy periods: mobile convenience can make me overconfident. A quick glance at a balance does not necessarily explain pending activity, timing, or the reason a total changed. I would use the app to observe and confirm, not to replace a complete understanding of my account. That approach makes the experience safer and prevents the small screen from turning a simple check into a mistaken financial conclusion.
Reliability is about recovery, not just opening
For me, reliability in banking means more than launching successfully. It means knowing whether the app has completed an action, whether the displayed information is current enough for the decision I am making, and what to do when something interrupts the session. Park National Bank earns its place on my phone when it gives me a dependable path back to that information without making me guess.
Recovery matters after a connection drop, an interrupted authentication step, or an app that returns from the background in an uncertain state. My preferred recovery sequence is conservative: reopen the app, check the account activity, and confirm the result before submitting anything again. If an action appears incomplete, I would rather verify than duplicate it. This is particularly important for payments and transfers, where a second attempt may create a problem even if the first screen did not provide immediate reassurance.
I also recommend closing the loop after important actions. If I make a change, I look for a confirmation and then revisit the relevant account activity when possible. That extra check takes little time and gives me a clearer record than trusting a button press alone. It is one of the most useful habits for any mobile banking app, but it is especially relevant here because the app’s job is to connect me with real accounts rather than offer a simulation.
The app has more than 100 thousand installs, and its review count is around 1.3 thousand. That gives it a meaningful user base without turning popularity into proof of flawless operation. I would still evaluate it on my own device, particularly if the phone is older or has limited free storage. A banking app should not be judged only by how it behaves on a new handset in ideal conditions.
Stability can also be affected by the surrounding phone environment. Aggressive battery saving, outdated system components, crowded storage, or a connection that changes between Wi-Fi and mobile data can make an otherwise normal session feel unreliable. If the app behaves strangely, I would first update the operating system and app, restart the phone, and try again on a stable connection. I would avoid installing unofficial copies or entering banking credentials into a page reached through an unexpected message.
Device constraints and the right kind of user
The minimum operating-system requirement is 11, so people using an older device may need to upgrade before they can use the current app. That is not a minor detail for banking customers who keep phones for many years. Before changing phones or resetting an old one, I would make sure I can still access the account through another approved route and that I have the information needed to complete sign-in again. A banking app should never be the only recovery plan.
On a newer phone, I would expect the app to be a modest resource compared with video, gaming, or social media applications because its purpose is focused account access rather than continuous content consumption. I would not, however, make a firm claim about battery use or storage impact without testing the exact device and version. What matters in daily use is whether it opens cleanly, handles a short banking session, and leaves the phone ready for other tasks.
Screen size changes the experience. A compact phone is convenient when I am standing in a shop or waiting for transport, but transaction descriptions and confirmation details deserve extra attention on a small display. A larger phone makes review easier, though it is still not the same as a desktop browser for comparing many entries. I would choose the phone app for immediate access and use a larger screen for careful reconciliation whenever the situation allows.
People who should consider it are Park National customers who want a direct mobile route for regular account checks and everyday banking tasks. It is also a sensible fit for someone who values a bank-specific experience over an account-aggregation service. People who should skip it include anyone without a Park National relationship, anyone running an operating system below the stated requirement, and anyone looking for a complete household budgeting workspace with accounts from many institutions.
The comparison with usual alternatives is straightforward. A mobile browser can provide broader web navigation and may feel familiar on a desktop, but it is less purpose-built for quick phone checks. A third-party finance app may offer stronger budgeting, categorization, or multi-bank visibility, but it introduces another layer between me and the bank and may be excessive for simple account access. Park National Bank occupies the middle ground: more direct than a browser for routine use, but narrower than a full financial-planning platform.
Privacy-minded routines improve the experience
Because this is a finance app, I would treat the phone itself as part of the security setup. I would use a screen lock, avoid signing in while someone can easily see the display, and be cautious on public networks. I would also review the account after any unusual interruption instead of assuming that an unfinished screen means nothing happened. These are not flashy features, but they determine whether mobile banking feels controlled or stressful.
I would be particularly careful with notifications and screenshots. A notification that reveals too much account information can be visible on a locked screen, while a screenshot containing transaction details can remain in a photo library or cloud backup. My practical rule is to keep sensitive previews limited and delete temporary images after they are no longer needed. This is a stronger everyday safeguard than simply choosing an app because it opens quickly.
Another useful tip is to keep the app’s role clear in my personal finance system. I use it for the bank relationship and immediate account awareness, while a separate budgeting method handles broader planning if I need that. Trying to force one bank app to become a complete financial organizer usually creates unnecessary friction. The narrower the task, the easier it is to notice when something does not look right.
Final performance verdict
After looking at speed expectations, busy-use situations, recovery, and device constraints, I see Park National Bank Mobile Banking App as a practical, focused choice for the customers it serves. Its strength is not spectacle. It is the ability to keep routine banking close at hand, with a clear purpose and a free entry point. The 4.4 average and broad install base support the view that it has found a useful role for many people, while the current version shows that the app remains actively relevant to its mobile audience.
My recommendation comes with a clear condition: use it as a direct banking companion, not as a replacement for every financial tool. It makes sense for checking activity during the day, confirming account details before spending, and recovering calmly after an interrupted session. It is less suitable for detailed budgeting, complicated financial comparisons, or anyone who needs one app to combine several banks.
The most important performance quality here is confidence after an action. If I can tell whether an account check or transaction-related step completed, the app is doing the job I need. If a screen is slow or interrupted, I verify before repeating anything. That habit turns a potentially frustrating mobile session into a controlled one.
For a Park National customer with a compatible phone, I would recommend installing it and keeping the operating system current. I would begin with simple balance and activity checks, learn the recovery routine before an urgent situation, and keep a browser or another approved access method available as a backup. Used with those expectations, this free app is a sensible everyday tool: focused, convenient, and strongest when I need a quick connection to my Park National account rather than a complete financial command center.
Pros
- Simple mobile banking interface for everyday account management.
- Quick access to balances, transactions, and account history.
- Mobile check deposit can save trips to a branch.
- Bill payment features help organize recurring payments.
- Security tools add protection for mobile banking access.
Cons
- Some features may vary depending on your account type.
- Mobile check deposits may have limits and delayed availability.
- The app may feel basic compared with larger national banks.
- Branch and ATM access can be limited outside its service area.
- Occasional updates or maintenance may temporarily affect access.
FAQs for Park National Bank
What is Park National Bank, and what can I do with its mobile app?
Park National Bank’s mobile app is designed to give customers convenient access to everyday banking services from an Android or iOS device. After signing in, you can typically review account balances and transaction history, transfer money between eligible accounts, pay bills, deposit checks using your phone’s camera, and locate branches or ATMs. Available features may depend on your account type, enrollment, and the bank’s current service availability.
Is the Park National Bank app safe to use for mobile banking?
The app is built for banking with standard security measures such as encrypted connections, secure login procedures, device authentication options, and account monitoring tools. However, no banking app can protect you if your credentials are shared or your device is compromised. Download it only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and enable biometric login when supported.
Can I deposit checks through the Park National Bank mobile app?
Eligible customers may be able to deposit checks remotely by photographing the front and back of an endorsed check within the app. The images must be clear, and the check should be endorsed according to the bank’s instructions. Deposit limits, processing times, funds availability, and eligibility can vary. Keep the original check safely until the deposit is confirmed, then follow Park National Bank’s retention and disposal guidance.
Does Park National Bank’s app support bill payments and money transfers?
The mobile banking experience generally provides tools for managing payments and moving funds, although the exact options depend on your account and enrollment. You may be able to pay companies or individuals through bill pay, transfer money between Park National Bank accounts, and possibly send funds to external accounts. Before scheduling a payment, review delivery dates, recurring-payment settings, fees, and recipient information carefully.
What should I do if I cannot log in or notice an unfamiliar transaction?
If you cannot access the app, first check your internet connection, confirm that the app is updated, and use the official password or username recovery process rather than third-party websites. Do not repeatedly guess credentials if your account may become locked. For an unfamiliar transaction, contact Park National Bank through the verified phone number or secure message option immediately, change your password, and review recent account activity and device access.

Park National Bank
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@parknationalbank.com, visit https://parknationalbank.com/, or review their https://parknationalbank.com/privacy/.










